
You can't see what you can use
Your home's value has moved and your loan has come down, but nobody has shown you the part a lender will let you borrow against. Without that number, every property you look at is a guess.
You've built equity in your home. The usable part of it can fund the deposit on an investment property without selling. It's borrowed against your home, so it's more debt, and your income has to support the new loan.
Book a Coaching Call and you leave with your usable equity worked out, the rules that apply where you'd buy, and a plan for your first purchase and the one after it.
For homeowners (or renters who own an investment property) with $100k+ in usable equity, a full-time income and $100k+ household income. The Delphi Scorecard checks where you stand in about a minute.
There's no cost and no obligation, and you keep your numbers whatever you decide. General information only. Delphi & Co does not provide personal financial or tax advice.
None of them is the property. They're the numbers and the rules that come before it, and they're what stops people with equity in their home from buying the investment property they've been thinking about.
Your home's value has moved and your loan has come down, but nobody has shown you the part a lender will let you borrow against. Without that number, every property you look at is a guess.
Lenders test you at a higher rate than you'll pay. Mortgage insurance starts above 80 per cent. Stamp duty and land tax change from state to state. Miss one and the property you've picked doesn't get approved, or costs more than you planned.
Buy the wrong property, in the wrong order or with the loan set up the wrong way, and it ties up the equity and borrowing you'd need for the next one. That's how a first investment property ends up being the only one.
Waiting doesn't fix any of it. It only means another year of planning without your real numbers.
Many people buy an investment property first and look for a plan second. That's the order that gets them stuck. We do it the other way round.
I've spent more than 12 years in property, and I built Delphi & Co to help people put the equity they've built to work in an investment property, and keep going from there. Delphi has a long track record of helping clients build portfolios with the equity in their home, and it's now all we focus on. Your numbers come first, then the rules, then the property that fits both.
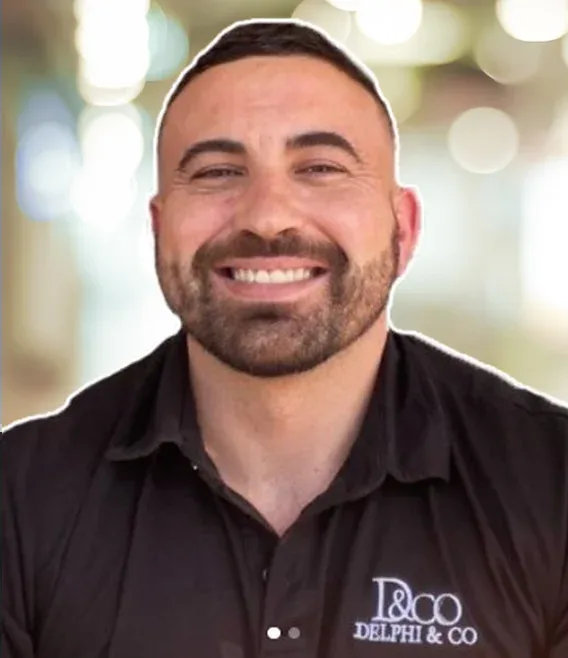
I'm Adel Pearce, founder of Delphi and Co. We help people use the equity they've built in their home to buy an investment property, and then build a portfolio from there. Many people buy a property first and look for a plan second. We do it the other way round.
We start with what you can actually use: your usable equity, your borrowing capacity, your income and your timeframe.
Then we guide you through the rules that trip people up, lending, stamp duty and land tax, and we find, analyse and negotiate the property through to settlement with you.
Fees are covered on your calls, before you commit to anything.
If you want to know what your equity can do, book a Coaching Call. My team and I will walk you through it.
Four things, in the order that keeps the next purchase possible: your number, the rules, the right property, and the plan for what comes after it.
Usable equity is the part of your home's value a lender will let you borrow against, less what you still owe. We get yours worked out, and your borrowing capacity confirmed by your broker, before you look at a single property, so you don't fall for one you can't buy.
Lending rules and state taxes, explained in plain English and handled in the right order.
Researched, analysed on its numbers, negotiated and managed to settlement, with the working shown to you.
We plan each purchase so it sets up the next: the order, the timing, and the equity and borrowing you'll need when it's time to buy again. After settlement we review it with you.
The Delphi Scorecard is a short self-assessment of your home, your income and your goals. You get a rough read on your usable equity straight away, and if your answers show you're ready, you pick your Coaching Call time at the end. The call then starts with your numbers.
No paperwork. A rough answer is fine for every question.
Illustrative layout · no real figures
About a minute on your home, borrowing and goals.
Pick a time at the end of the Scorecard. You leave with your usable equity worked out, the rules that apply where you'd buy, and a plan for your first purchase and the one after it.
Your actual figures, from the documents you upload before the call.
The agreement and the fees in writing. Nothing is signed on the call, and the decision stays yours.
You don't need years of savings for the deposit. Everything we do starts with the usable equity in your home, and we plan the first purchase with the next one in mind.
Equity built up in your own home can fund the deposit and costs on an investment property without selling it. It's borrowed against your home, so it's a loan, and your income has to support it.
Read the home equity guide →One property is a purchase. A sequence of properties, bought in the right order, is a portfolio. We plan the next acquisition before the first one settles.
Read the portfolio guide →We work with homeowners (or renters who own an investment property) who work full time (employed or self-employed), have a household income of $100,000 or more and have about $100,000 or more in usable equity. That's where buying with your equity starts to work.
Not there yet? The Scorecard shows where you stand, and we'll check in as things change.
Check where you stand →Many first-time investors get caught on the rules, not the property. These are the six that matter before you buy. We take you through each one in the right order, and bring in independently licensed professionals for the regulated parts.
Lenders test your borrowing at a buffer above the actual rate, and count rental income and existing debts in their own way. We plan with your broker so the purchase fits what lenders will approve.
Borrowing more than 80 per cent of a property's value usually means lenders mortgage insurance. We plan the deposit from your equity around it.
Each state and territory sets its own stamp duty and land tax, with different rates and thresholds for investors. We put them into every property's numbers.
Deductions, depreciation and how the property is owned are tax questions. We make sure they're asked before you buy, not after.
Employed full time, lenders look at your recent payslips; self-employed, at your last two years' tax returns. Other debts, including credit card limits, count against what you can service.
Building and pest inspections, strata records, zoning and contract conditions, reviewed before you sign.
On the call we go through the rules that apply where you'd buy. General information only. Delphi & Co does not provide personal financial, tax or legal advice.
A Coaching Call to work out your usable equity, borrowing capacity, goals and timeframe. We show you plainly where your numbers stand, as general information; the decision is always yours.
Your portfolio plan: how much to buy, where, in what order, and the ownership structures people commonly use, explained in general terms. Advice on structure and finance comes from the licensed specialists we coordinate.
We research target areas and identify properties that fit the plan, then analyse each one on its numbers: price, rent, costs and growth drivers.
We negotiate the purchase and manage the process through contract, due diligence and settlement, keeping you informed at each step.
After settlement we review your equity and borrowing with you and plan the next purchase, when they support it.
Fees are covered on your calls, before you commit to anything. They're never quoted in ads.
Delphi & Co is a licensed buyer's agent. We work for you, to get you the best outcome.
Financial advice and lending come from separate, independently licensed professionals. Whether a structure suits you is a question for those licensed professionals.
Each property we put forward comes with the numbers we used to assess it.
Delphi & Co was founded by Adel Pearce, a buyer's agent and investment property specialist with more than 12 years in property. Your Coaching Call is with one of the specialists below.
Founder · Director
Buyer's agent and investment property specialist. Built the Delphi Method and leads strategy for every client.

Investment Property Specialist
Works with clients from the first Coaching Call through to strategy and purchase.

General Admin · Principal's Secretary
Keeps the paperwork and the process running smoothly for every client, from the first call to settlement.
Plain-English guides to usable equity, borrowing and building a portfolio. Read one tonight, then take the Scorecard to see your own numbers.
How the usable equity in your home can fund the deposit and costs on an investment property, explained step by step in plain English.
Read the guide →ExplainerThe difference between equity and usable equity, how lenders work it out, and how to get a rough figure for your own home in two minutes.
Read the guide →GuideHow one well-planned purchase becomes the base for the next, and how usable equity, cash flow and yearly reviews turn properties into a portfolio.
Read the guide →The questions people ask before their Coaching Call, answered straight.
There's no cost and no obligation, and you keep your numbers whatever you decide. Fees are covered by your investment property specialist on the calls, and set out in the agreement before you sign. We never quote them in ads.
Many people aren't ready on day one, and that's what the call is for: you find out where you stand before you decide anything. If the timing isn't right, you'll know what would change it. Start with the Scorecard; it takes about a minute.
That's a good instinct. Pick a Coaching Call time you can both join, so you both hear the same numbers and ask your own questions. Two incomes and a jointly owned home can look quite different from either of you alone.
You can, and some people do. What catches people is the order: equity and borrowing confirmed before the property, the state taxes in the numbers, and a purchase that leaves room for the next. We run that order with you, and licensed brokers and accountants handle the regulated parts.
It's where we show you how Delphi works and what we'd do for you, and it starts with your numbers from the Scorecard, so it's about you first. There's no countdown and no pressure. If it isn't the right time for you, your specialist says so and says what would change that.
It's the part of your home's value a lender will let you borrow against, less what you still owe. Lenders commonly lend up to 80 per cent of the value without mortgage insurance. Your lender or broker confirms your real figure; we work it out with them.
Homeowners (or renters who own an investment property) who work full time (employed or self-employed), have a household income of $100,000 or more before tax and have about $100,000 or more in usable equity in their home or investment property. The Delphi Scorecard shows where you stand in about a minute. If you're not there yet, we'll send you useful information and check in as things change.
Delphi has a long track record with SMSF property purchases. The rules have changed, and we help you navigate them. It isn't our main offer any more, but if you'd like to know more, ask us about SMSF. Whether an SMSF suits you is a question for a licensed financial adviser. If you own your home, our main service is buying an investment property using its usable equity.
No. We don't provide personal financial or tax advice. Where your strategy needs advice or lending, we coordinate separate, independently licensed professionals.
We're based in Queensland and work with clients across Australia. Calls are by video, at a time that suits you.
Book a Coaching Call and leave with your usable equity worked out, the rules that apply where you'd buy, and a plan for your first purchase and the one after it. It starts with the Delphi Scorecard, so the call starts with your numbers.
There's no cost and no obligation, and you keep your numbers whatever you decide.
Or call 1800 577 526 · info@delphiandco.com